Arctic Sovereignty in the Age of Great Power Competition
A comprehensive analysis of Greenland's sovereignty paradox, rare earth resource potential, and the US-China-Denmark strategic triangle — mapping why true independence may be structurally unattainable and what that means for Arctic investment positioning.
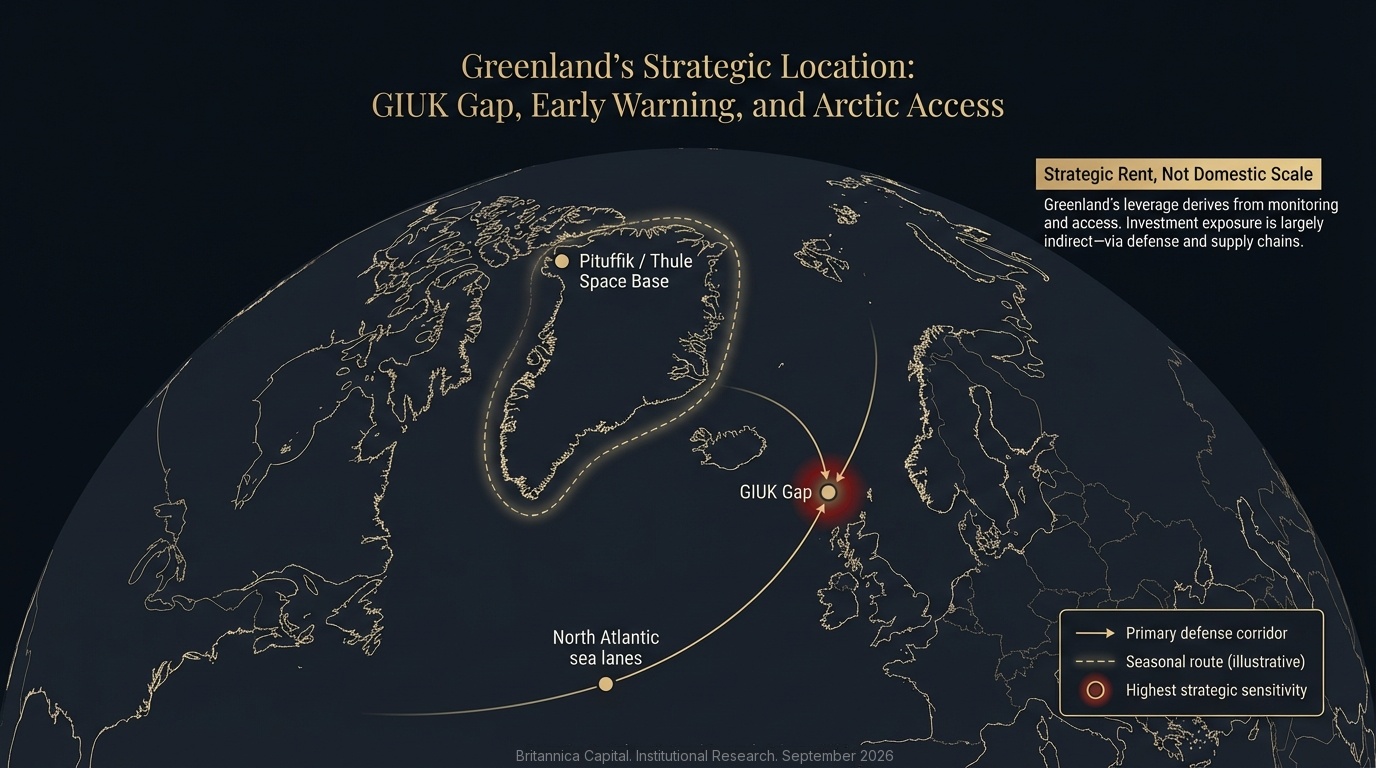
Greenland's Strategic Location
Greenland sits at the intersection of three critical domains — Arctic shipping routes opening with ice melt, the GIUK gap controlling North Atlantic naval access, and some of the world's largest untapped rare earth and critical mineral deposits. Its geography makes it indispensable to US missile defence architecture and NATO's northern flank.
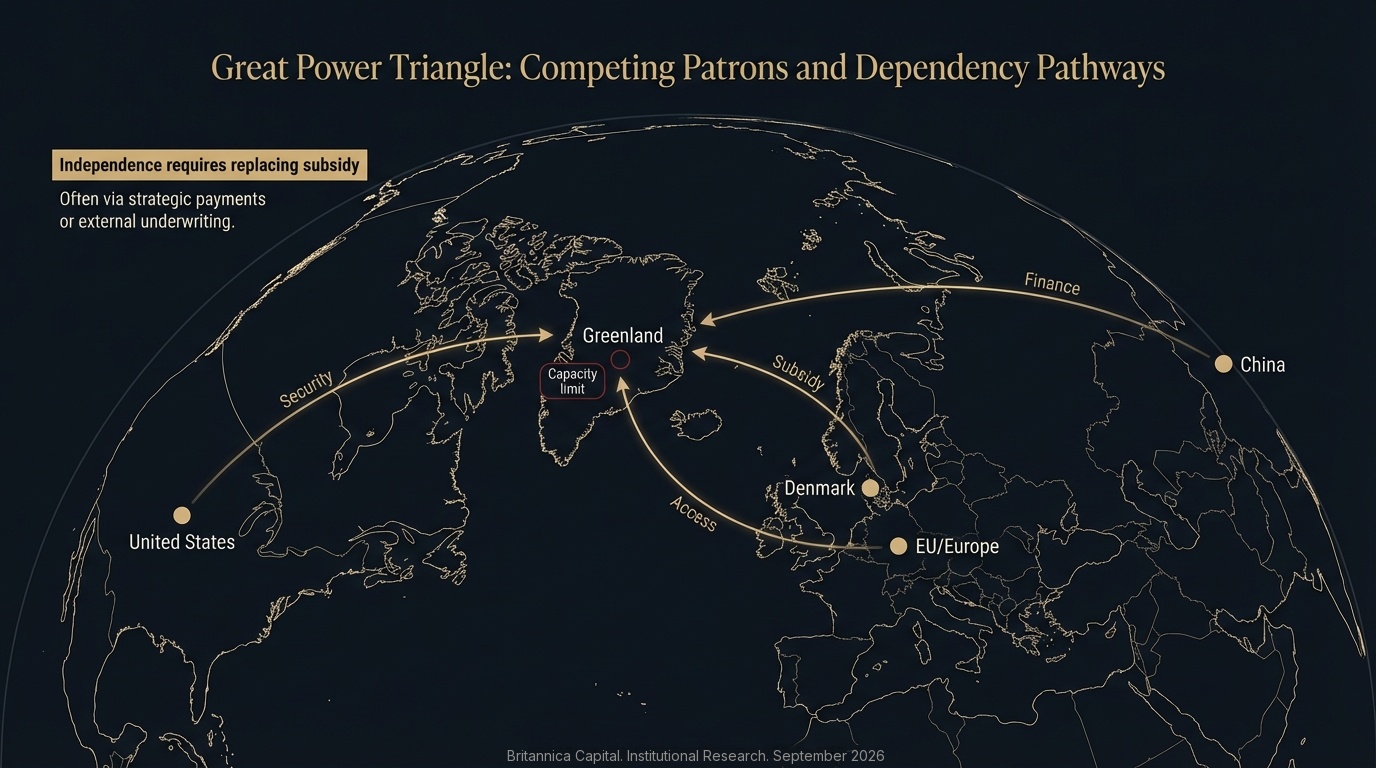
The Great Power Triangle
Greenland is caught between three competing patrons: the US seeking military basing and rare earth supply security, China pursuing critical mineral access and Arctic shipping routes, and Denmark balancing colonial legacy with strategic relevance. Eight months of open US pressure in 2026 — tariff threats, a January "framework", closed-door basing talks and a renewed July demand for control — have raised the stakes without changing the structure. Each relationship offers funding but demands alignment — making true sovereignty a structural paradox.
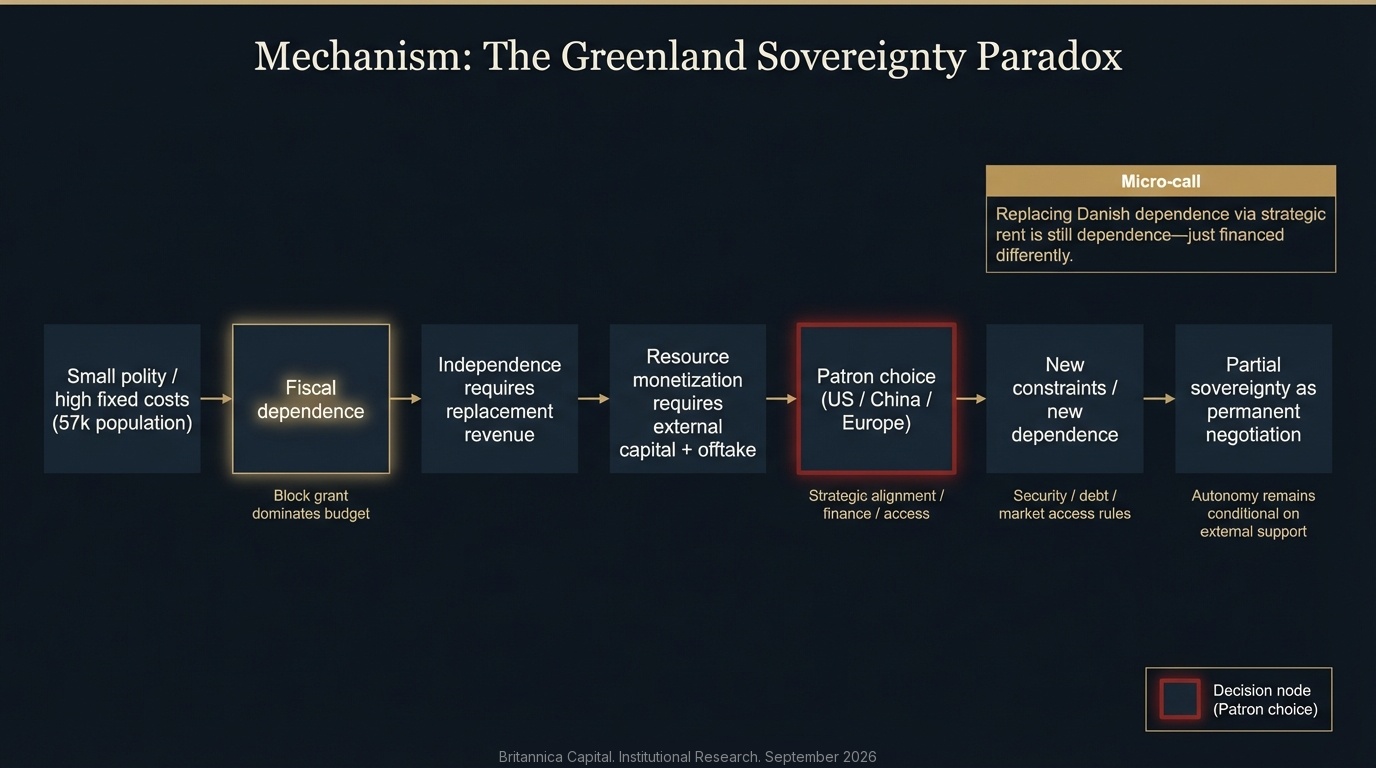
The Greenland Sovereignty Paradox
To achieve independence from Denmark, Greenland must replace a $600 million annual subsidy with resource revenue or strategic payments. Yet developing resources requires choosing an external patron — Chinese capital, American military payments, or European integration — trading one dependence for another.
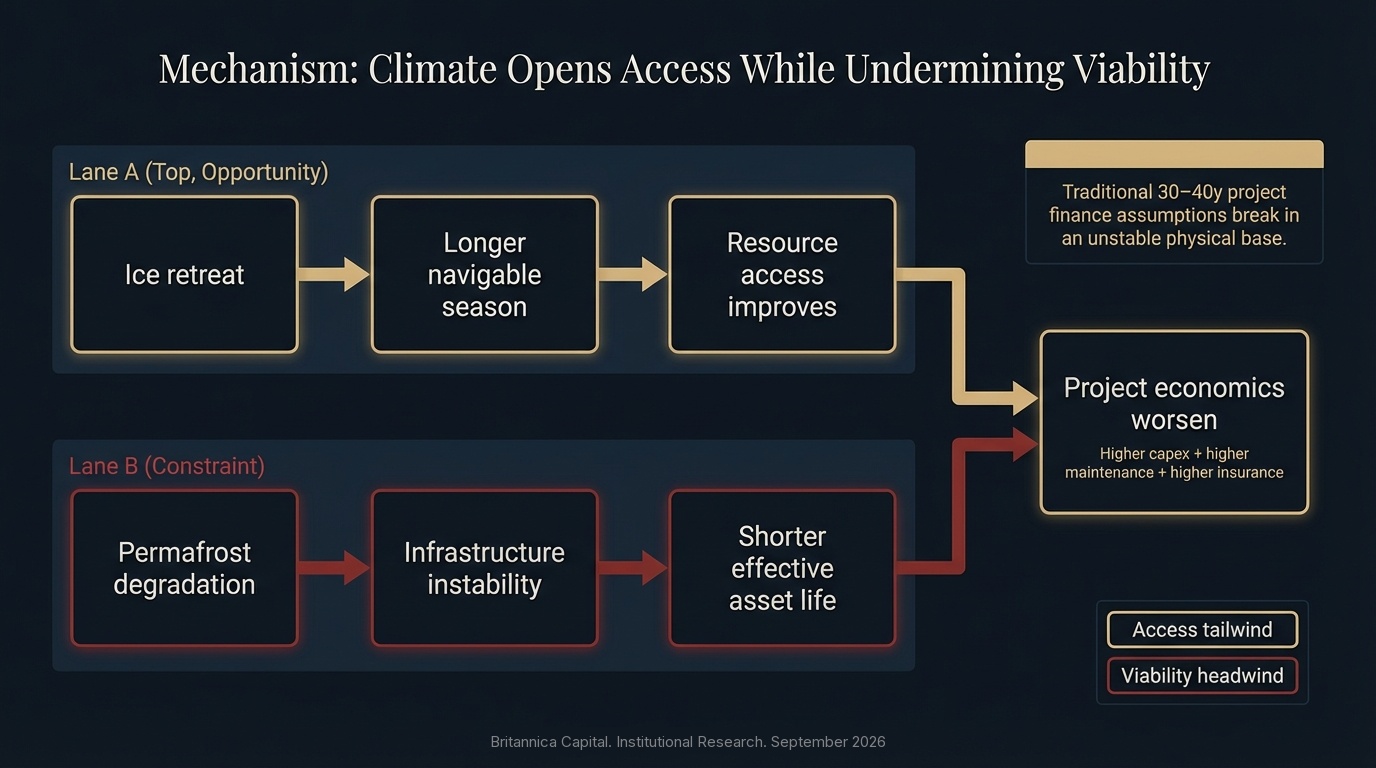
Climate Opens Access While Undermining Viability
Accelerating ice melt simultaneously unlocks mineral deposits and shipping corridors while destabilising Greenland's physical infrastructure, fisheries, and coastal settlements. For investors, Greenland is not a direct opportunity but an indicator — watch it for Arctic trends and rare earth supply dynamics, then invest in liquid adjacent markets.
Greenland represents one of the most complex geopolitical transitions in modern Arctic history: a microstate of 57,000 people sitting atop resources that great powers need, navigating between colonial legacy and aspirational independence, watching its physical foundation literally melt beneath it. The first eight months of 2026 — a US tariff threat against eight European allies, a Davos "framework" that ruled out force, trilateral talks that Nuuk says are "ongoing", a NATO command umbrella for the Arctic, and a renewed presidential demand for control in July — have made the territory more salient than at any point since 1945. They have not changed its arithmetic.
This report challenges the consensus narrative that Greenland is on an inevitable path toward independence and resource-driven prosperity. Instead, we argue Greenland faces a fundamental paradox: to achieve independence from Denmark, it must replace a $600 million annual subsidy with resource revenue or strategic payments. Yet developing resources requires choosing an external patron—Chinese capital, American military payments, or European integration. Each path trades Danish dependence for new dependence. True sovereignty may be structurally unattainable for a territory this small, this remote, and this expensive to operate.
For investors, Greenland is not an opportunity but an indicator: watch it to understand Arctic trends, rare earth supply dynamics, and US-China competition, then invest in liquid adjacent markets.
The Melting
Foundation
Greenland's geography is not static backdrop—it is the primary variable determining whether the territory becomes economically viable. The ice sheet covering 80% of Greenland's 2.2 million km² is melting at accelerating rates, unlocking resources while simultaneously destroying infrastructure.
Only 56,000 km²—roughly 2.5% of total area—is ice-free and habitable. The ice sheet, up to 3km thick, holds 10% of the world's fresh water. Satellite gravimetry puts average ice loss at roughly 265 billion tons a year over 2002–2025 (NASA GRACE/GRACE-FO), up from ~50 billion tons in the early 1990s. Individual years vary widely: the September 2025–August 2026 melt year lost about 173 billion tons, the 30th consecutive year of net loss according to the Geological Survey of Denmark and Greenland (GEUS). The long-run trend, not any single season, is what matters for infrastructure planning.
For Greenland's economy, ice melt creates a paradox. Retreating glaciers expose mineral deposits previously inaccessible. Coastal waters become navigable for longer seasons. But permafrost degradation undermines existing infrastructure. Airports face runway instability. Roads crack and subside. A mine built today might have a 20-year window before permafrost collapse makes it uneconomic. Traditional project finance models assuming 30–40 year asset lifespans don't accommodate this instability.
- Permafrost degradation affects ~85% of ice-free land; buildings, roads, and runways subsiding
- Coastal erosion accelerating as protective sea ice disappears
- Fishing grounds shifting — shrimp declining, cod migrating north
- Glacial outburst floods becoming more frequent and destructive
- Settlement relocation required (e.g., Uummannaq, pop. 1,400)
Greenland's value to external powers is primarily strategic rather than economic. The GIUK Gap (Greenland–Iceland–UK) is NATO's primary Atlantic defence line for tracking Russian submarines. Thule Air Base (Pituffik Space Base) hosts ballistic missile early warning radars and satellite tracking—the northernmost US military installation. Since February 2026 NATO has grouped allied Arctic activity under a single command umbrella, Operation Arctic Sentry (led by Joint Force Command Norfolk), while Denmark's Arctic Endurance 26 exercise series has rotated eight allied contingents through Greenland during the year. Arctic shipping routes could reduce Asia-Europe distances by ~4,000 nautical miles, though economic viability remains overstated: Russia's Northern Sea Route carried about 37 million tonnes in 2025, of which only ~3.2 million tonnes was transit traffic across 103 voyages, with an open-water window of roughly two weeks — a rounding error against Suez, and dependent on nuclear icebreaker escort.
From Colony
to… What?
Denmark-Norway colonised Greenland in 1721 under Hans Egede. For 250 years, Greenland existed as a closed colony—no outside contact allowed, trade monopolised by the Danish crown, Greenlanders isolated from the broader world. This created total dependency: no experience with external trade, no capital accumulation, no institutional development beyond what Danish administrators provided.
WWII brought de facto American administration. The US built bases including Thule, then offered to purchase Greenland for $100 million. Denmark refused but signed the 1951 Defence Agreement allowing Thule operations—without consulting Greenland's government. The base construction forcibly relocated 116 Inuit from their hunting grounds, given 24 hours notice. This remains a source of deep grievance.
Home Rule (1979) gave Greenland its own parliament and control over domestic affairs. Denmark retained foreign affairs, defence, and monetary policy. The subsidy continued. In 1985, Greenland became the only territory to leave the European Economic Community—over fishing rights. The 2008 Self-Government Act included a provision: every dollar of mining revenue would reduce the subsidy by an equivalent amount. This creates a dependency loop—Greenland cannot keep the subsidy if it develops resources, but cannot develop resources without it.
"The 2019 Trump purchase offer was widely mocked, but it reflected strategic logic: the Pentagon saw growing Chinese interest in Greenland and wanted to preempt Chinese influence. The episode brought Greenland to global attention and accelerated the debate about its future status."Britannica Capital Research, September 2026
The 2021 election proved decisive. Inuit Ataqatigiit won on a platform of banning uranium mining and blocking the Kvanefjeld rare earth project. Greenland Minerals' stock collapsed 90%; the company, since renamed Energy Transition Minerals, opened arbitration against Greenland and Denmark in 2022. In June 2026 the government formally refused to renew the Kvanefjeld exploration licence, ruling that further work was unlikely to yield a deposit exploitable under the Uranium Act. This reversed eight years of loosening mining restrictions and closed the uranium-bearing mining path to independence for the foreseeable future.
Trump's return in 2025 renewed US interest, and 2026 turned it into open pressure. In early January the President declined to rule out force; on 14 January Danish and Greenlandic foreign ministers met the Vice President and Secretary of State in Washington and left citing a "fundamental disagreement"; on 17 January a 25% tariff was threatened against Denmark and seven other European countries, and an estimated 20,000 people marched in Copenhagen and 4,000 in Nuuk under "Hands off Greenland". At Davos on 21 January the President ruled out military force and described a "framework" with the NATO Secretary General covering expanded basing, resource access and allied Arctic security; the tariff threat lapsed and three-party talks were launched on 28 January. By mid-May Nuuk reported "progress" in closed-door talks understood to centre on expanded US basing, while repeating that the island is "not for sale"; a US consulate opened in Nuuk on 21 May. On 7 July, at the NATO summit in Ankara, the President revived the demand that Greenland "should be controlled by the United States", and on 31 July predicted US control before his term ends in January 2029. On 2 September Greenland's foreign minister told the European Parliament that dialogue with Washington is "ongoing". Literal purchase remains off the table for Copenhagen and Nuuk alike; expanded US access, and payments attached to it, are the live negotiating object. Greenland must still navigate carefully—too close to the US risks appearing to exchange Danish dependence for American control.
The Subsidy
Trap
Greenland is not an economic system generating value through production and exchange. It is a fiscal transfer mechanism that converts Danish subsidies and fishing quotas into employment and public services for 57,000 people living in extreme remote conditions.
Greenland's GDP is roughly $3.3 billion (2023), yielding per-capita GDP of ~$58,000. This statistic is misleading—it represents subsidy consumption, not productivity. The Danish block grant of ~DKK 4 billion (~$600M) supplies roughly half of the self-rule government's revenue. Per capita, that is about $10,500 annually—more than many countries' entire per-capita GDP. Public-sector employment accounts for roughly 40% of the workforce (vs. 15–20% in developed economies).
To achieve fiscal independence, Greenland must increase revenue by ~$900M (4.5× current), cut spending by 75%, or find alternative patrons willing to provide $600+ million annually. None are realistic on foreseeable timelines.
~$500–550M in annual exports — 90% of goods exports. Primary species: coldwater shrimp (declining as waters warm), Greenland halibut, snow crab, and cod (newly appearing).
Royal Greenland (government-owned) dominates with ~2,000 employees but operates at breakeven or loss most years. Fishing alone covers perhaps 15–20% of what independence would require.
Mining: Repeated pattern of exploration, feasibility studies, and abandonment. Kvanefjeld (licence renewal refused June 2026), Isua iron ore (abandoned), offshore oil (12 dry holes; new licensing halted in 2021). The exceptions are small: Nalunaq gold, restarted by Amaroq in 2024, produced ~9,000 oz in the first half of 2026, and Tanbreez, the flagship non-uranium rare-earth project, is at pilot-plant stage with first ore targeted for late 2028–early 2029 and a $120M US EXIM letter of interest rather than committed finance. Infrastructure costs ($50–100M/km for roads) exceed mineral value at current prices.
Tourism: ~100K visitors, ~$50–75M revenue. Nuuk's international airport (late 2024) and Qaqortoq's new airport (April 2026) widen access, but in August 2026 the government asked cruise operators to limit fjord calls on noise and wildlife grounds. Even aggressive growth to $150–200M by 2035 cannot transform the fiscal picture.
The Bull Case for
Greenland Sovereignty
A serious analysis must address the strongest counterargument: that Greenland is entering a regime shift, not a continuation of the subsidy trap. The bullish case rests on a simple proposition: Greenland does not need to "replace the Danish subsidy" through normal economic development. It can replace it through geopolitical rent extraction at exactly the moment the world is rediscovering the Arctic as a strategic theatre.
Strategic Access Compact
Greenland becomes an Arctic host-nation support state whose core revenue comes from US/NATO base payments rather than domestic production. There is little precedent for Washington paying a host at scale—allies such as South Korea and Japan contribute toward US basing costs, not the reverse—but the closed-door basing talks under way since May 2026 and the US envoy's July proposal for a US–Greenland joint investment fund put the mechanism on the table. An arrangement worth $200–500M a year would be transformative.
REE as Security Commodity
If the West re-prices rare earths as strategic goods rather than market commodities, projects become viable via state-backed financing, non-market offtake agreements, and loan guarantees. Security logic is rising.
Climate Opens Access
Melt relaxes Greenland's historic choke point—access. Extended coastal seasons, reduced ice risk premiums, and more construction days compound into meaningful feasibility improvements.
Independence Attracts Capital
Sovereign status grants full treaty-making power, clarifies regulatory authority, and could trigger a nation-building phase attracting skilled diaspora, international partnerships, and institutional capacity.
Rebuttal: Even in its strongest form, the bull case runs into the central paradox — replacing Danish dependence by monetising strategic access is not the same as sovereignty; it is sovereignty financed by patronage.
Sovereignty Without
Capacity
Opinion polling consistently shows a majority of Greenlanders—roughly 56–60% in 2025 surveys—support eventual independence. But the support is conditional: around 45% oppose it if it means a fall in living standards, and when asked to choose between Denmark and the United States, 85% chose Denmark against 6% for the US. This gap reflects honest assessment of economic reality. It has also shaped politics: all party leaders issued a joint statement on 9 January 2026 that Greenlanders "do not want to become Americans", the Premier declared "we choose Denmark, NATO and the EU" four days later, and a broad parliamentary majority has ruled out an independence referendum in the current term. The governing coalition itself narrowed when Siumut withdrew on 13 March 2026, leaving the Democrats, Inuit Ataqatigiit and Atassut with 19 of 31 seats. A generational divide compounds: younger Greenlanders push for earlier independence; older Greenlanders remember harder times before Danish modernisation.
The uncomfortable conclusion: true independence may be structurally impossible for a territory with Greenland's population and resources. A 57,000-person state cannot afford the specialised expertise required for modern governance across mining law, offshore regulation, trade negotiations, monetary policy, defence, aviation, maritime law, and more. Even wealthy small states (Luxembourg, Singapore, Iceland) outsource extensively.
Denmark cannot abandon Greenland without international condemnation. But continuing subsidies faces growing domestic opposition. Denmark's strategy is subtle: support Greenland's right to independence while maintaining economic structures that make independence prohibitively expensive. The 2008 Self-Government Act's one-for-one subsidy reduction ensures Greenland never gets ahead—first dollar of resource revenue replaces first dollar of subsidy.
Denmark also benefits strategically: Arctic Council membership, expanded EEZ claims, NATO relevance, European credibility as an Arctic power. If Greenland left, Denmark would lose all of this. Copenhagen is now paying for that relevance: an October 2025 Arctic defence package of DKK 27.4bn (~$4.25bn) funds a new Joint Arctic Command headquarters, additional Arctic vessels and drones, and Denmark's first 11-month conscript cohort is rotating into Greenland in September 2026. The 24 March 2026 general election was fought under the shadow of US pressure and returned Mette Frederiksen, whose third cabinet took office on 2 June; Greenland's two Folketing members used the coalition talks to press for more Greenlandic say over foreign policy.
Greenland has one of the world's highest suicide rates (~83 per 100,000 vs. global average ~10). Alcoholism and domestic violence are epidemic. These pathologies reflect cultural disruption, limited economic opportunity, and extreme Arctic conditions. Any investment thesis depending on stable, skilled local workforce must account for high training dropout rates, substance abuse, and the inability of remote settlements to attract or retain skilled workers.
The Strategic
Triangle
United States
Wants: Expanded basing beyond Pituffik (closed-door talks since May 2026), "Golden Dome" sensor sites, rare earth access, denial of Chinese presence — and, in the President's words at Ankara in July, control "by the United States, not by Denmark". The special envoy's July recommendations were narrower: direct shipping links, more diplomats, an Arctic-focused State Partnership Program, a joint investment fund, exchanges. Offers: Nothing disclosed; a January "framework" and a Nuuk consulate (May 2026) so far. Risk: Trades Danish dependence for American dependence.
China
Wants: Port access, mining projects with offtake, diplomatic alignment, wedge in NATO. Offers: Belt & Road financing (loans, not grants), technical expertise, no political conditions. Reality check: China's Greenland footprint has shrunk — the Isua licence was revoked, Kvanefjeld is blocked, and Shenghe's ~7% stake in Energy Transition Minerals is its main residual exposure; Beijing's 2026 Arctic energy has gone into the Russian Northern Sea Route instead. Risk: Debt-trap model familiar from Africa and Pacific islands.
Europe / EU
Wants: Rare earth access (Greenland holds 25 of the EU's 34 critical raw materials), fishing quotas, Arctic governance role, Western alignment. Offers: €225M for 2021–27 (~€32M/yr) plus ~€17M/yr under the fisheries agreement; a proposed €530M for 2028–34; French and Canadian consulates in Nuuk (February 2026); and a strengthened EU–Greenland partnership declaration during the Commission President's 1 September 2026 visit. Risk: Cannot/will not replace Danish subsidy at scale.
Our January assessment was that Greenland's leverage peaked around 2019–2021 and was declining. 2026 forces a partial revision: salience is at a post-war high, but salience is not leverage. The territory has never been discussed more — tariff threats, a Davos "framework", a NATO command umbrella, consulates opening, a presidential prediction of US control "by 2029". Yet every one of those developments was initiated by outside powers, and Greenland's response has been to bind itself more tightly to Copenhagen, NATO and Brussels rather than to auction access. Its negotiating position is mediated through Denmark; the talks that matter are closed-door and Danish-led; and the mining path remains as closed as it was in 2021 — the June refusal of the Kvanefjeld licence made that explicit.
The narrative "Greenland's moment is coming" therefore still looks backwards. Attention has returned; the capacity to convert it into unconditional revenue has not. The current trajectory is rising salience with unchanged structural dependence.
| Ice Melt | Competition | Prices | Leverage | Likely Outcome |
|---|---|---|---|---|
| Fast | High | High | Maximum | Choose patron, extract maximum payment |
| Fast | High | Low | High | Strategic value dominates; US likely winner |
| Fast | Low | High | Medium | Mining develops without geopolitical premium |
| Slow | High | Low | Low–Med | Status quo continues, limited engagement |
| Slow | Low | Low | Low | Indefinite Danish subsidy, slow drift |
Market Implications:
Investing Around, Not In
Greenland has no stock exchange, no bond market, no derivatives, no currency (uses Danish krone). The only direct exposures are Energy Transition Minerals (ASX: ETM, formerly Greenland Minerals — collapsed 90% after 2021 and refused a licence renewal in June 2026), Critical Metals (Nasdaq: CRML, which controls Tanbreez but is pre-feasibility and moved 18–23% in single sessions in August 2026), Amaroq (AIM: AMRQ, a small gold producer), speculative penny-stock juniors, and government-owned entities (Royal Greenland, Air Greenland) that are not traded. Since meaningful direct exposure is unavailable, the framework favours positioning in adjacent markets.
If Greenland's deposits remain offline (base case 70% probability through 2030), existing non-Chinese producers benefit from constrained supply.
US Arctic capability is underdeveloped. Russia has 40+ icebreakers; the US Coast Guard operates three (one heavy), with the first new Polar Security Cutter not expected before 2033 and eleven medium Arctic Security Cutters planned from 2028. NATO's Arctic Sentry command and Denmark's DKK 27.4bn package point to rising Arctic defence spending over 5–10 years.
- Do not buy Energy Transition Minerals expecting project revival. The June 2026 licence refusal confirmed that the 2021 political consensus against uranium mining will persist for at least a decade.
- Do not assume "Greenland opening up" means mining boom. The 2021 election closed the uranium path and the flagship non-uranium project, Tanbreez, does not target first ore before late 2028. The narrative is outdated.
- Do not invest in Greenland tourism infrastructure — season is 3–4 months, access limited, costs extreme. Boutique market, not institutional.
- Do not expect Greenland government bonds. Denmark finances through direct transfers, not loans.
- Do not bet on literal US purchase. Enhanced payments for base rights are plausible; sovereignty transfer is not, whatever the July 2026 prediction of US control "by 2029". Both Copenhagen and Nuuk have restated that the island is not for sale.
Sovereignty as
Permanent Negotiation
"The ice sheet will continue melting. Great powers will continue competing. Greenlanders will continue negotiating. And capital should position not for the Greenland that romantic narratives promise, but for the Greenland that structural realities permit."Britannica Capital Research, September 2026
Greenland is geopolitically important but economically marginal, strategically valuable but politically constrained, resource-rich but development-poor. The romantic narrative—indigenous people reclaiming sovereignty, Arctic frontier opening, resource bonanza emerging—is appealing but empirically unsupported.
True sovereignty may be impossible not because of lack of will among Greenlanders, but because the modern state system requires scale, resources, and geographic advantages Greenland doesn't possess. Greenland's future likely involves permanent negotiation of partial sovereignty—choosing between Danish subsidies, American security payments, or Chinese infrastructure loans. The next markers are concrete: whether the US–Denmark–Greenland basing talks produce disclosed terms before year-end; whether the Tanbreez pilot plant and bulk sample convert an EXIM letter of interest into committed finance; whether the EU's proposed €530M envelope survives the 2028–34 budget negotiation; and whether the Kvanefjeld arbitration produces a ruling that re-prices Greenland's regulatory risk.
| 2030 Scenario | Prob. | Description | Investment Implication |
|---|---|---|---|
| Status Quo Plus | 45% | Danish subsidy continues; mining closed; tourism to $100–150M; population declines to ~55K | REE constraint continues (positive MP/LYC); Arctic development slower than bulls expect |
| Enhanced Autonomy | 25% | Limited non-uranium mining opens; US pays $200–300M/yr for expanded Thule; fiscal gap narrows | Modest REE competition; Nordic construction benefits; defence contractors see Arctic budget increases |
| Fiscal Crisis | 15% | Denmark cuts subsidy; forced to accept Chinese financing; NATO cohesion weakens | Defence spending surges; rare earth supply shifts to China-aligned Greenland; geopolitical vol rises |
| Oil Discovery | 5% | Major offshore find transforms fiscal picture; independence within 10–15 years; "Arctic Norway" | Negative oil prices; positive Arctic offshore services; changes Greenland from dependent to resource power |
| Climate Catastrophe | 10% | Ice loss accelerates beyond projections; settlements require emergency relocation; humanitarian crisis | Arctic development narrative collapses; insurance reprices Arctic risk; climate adaptation spending rises |
For institutional investors, Greenland is best understood as indicator rather than opportunity. Monitor it to understand Arctic development pace, US-China competition intensity, rare earth supply dynamics, and defence spending priorities. Then invest in liquid markets that benefit from those trends — rare earth producers if Greenland stays closed, defence contractors if US Arctic spending rises, Nordic logistics if Arctic shipping grows. Size positions based on conviction about broader trends, not Greenland-specific developments. Recognise that timelines are longer and probabilities lower than promotional literature suggests.
- Population: Statistics Greenland (Grønlands Statistik), 56,945 at 1 July 2026.
- Block grant and GDP: Danish block grant ~DKK 4bn (2023, Danish state budget); GDP $3.3bn and per-capita ~$58,000 (2023 estimates). USD conversions approximate.
- Ice loss: NASA GRACE/GRACE-FO ice-sheet indicator (2002–2025 mean, page updated July 2026); GEUS/Polar Portal melt-year balance reported 1 September 2026.
- Sea ice and shipping: NSIDC Sea Ice Today (September 2025 minimum 4.60M km²; late-August 2026 extent ~11th lowest); Centre for High North Logistics and High North News, NSR 2025 season (December 2025).
- US–Denmark–Greenland relations: OSW Centre for Eastern Studies (16 January 2026); Reuters, BBC, CNBC, Bloomberg, Fortune and Newsweek reporting, January–September 2026; Government of Greenland statements.
- Defence: Defense News on NATO Arctic Sentry (11 February 2026); Breaking Defense (14 January 2026); Danish Ministry of Defence Arctic package as reported September 2026; US Coast Guard Polar Security Cutter programme status (2026).
- Minerals: Critical Metals Corp. release (17 April 2026); Wood Mackenzie, Greenland rare earths (22 January 2026); Mining Weekly and Mining Journal on the Kvanefjeld licence decision (29 June 2026); Amaroq H1 2026 results (12 August 2026).
- EU: European Commission international partnerships, Greenland programme (2021–27 and 2028–34 proposal); Arctic Today (1 September 2026).
- Polling: published 2025 surveys as compiled in public reference sources; percentages rounded.
This material has been prepared by Britannica Capital for informational purposes only and does not constitute investment advice or a recommendation, offer to sell, or solicitation of an offer to buy any security or interest in any investment vehicle. Any such offer will be made only by a confidential offering memorandum and only to qualified investors. Past performance is not necessarily indicative of, or a guarantee of, future results. All investments involve risk, including the possible loss of principal. Strategies discussed may involve exposure to Arctic equities, commodities, rare earth markets, and geopolitically sensitive regions, all of which carry elevated volatility and concentration risk. Projections, targets, and forward-looking statements are based on assumptions and subject to change; actual results may differ materially. References to indices and commodity prices are for illustrative comparison only; indices are unmanaged and not directly investable. Opinions reflect the judgment of Britannica Capital as of the date indicated and are subject to change without notice. Geopolitical situations evolve rapidly, and readers should conduct independent analysis before making investment decisions.